
Estimate your monthly payments and budget for your next car with ease.
Calculate Your Estimated Monthly
Estimated Monthly Payment*
$1.338/Month
for 3 years
Loan Summary
Car Price$46.300
Down Payment-$400
Trade In Value-$0
Est. Interest (1.20%)+$880
Est. Sales Tax (3.00%)+$1.389
Other FeesNot Included
Total Loan Amount
$48.169
Monthly Payment
$1.338
Under $15k
Under $30K
Under $100K
Under $60K
Under $60K
Under $15k
Under $30K
Under $80K
Under $40K
Under $60K
Under $100k
Under $70K
Under $20K
Under $30K
Under $25K
What is an Auto Loan?
How to Calculate an Auto Loan?
Budget & Car Price?
Down Payment?
Trade-In Value?
Sales Tax?
Interest Rate?
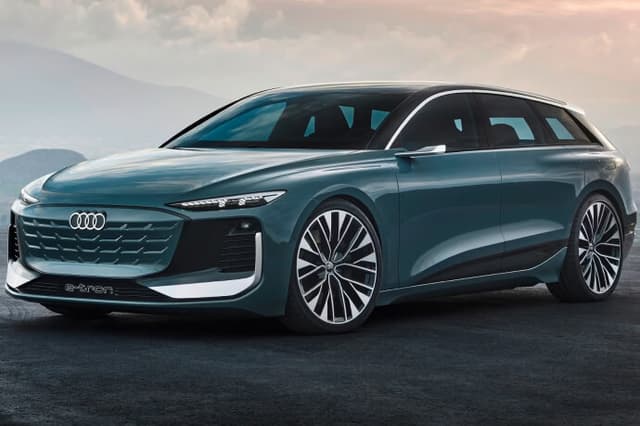
Audi A6 Avant E-Tron
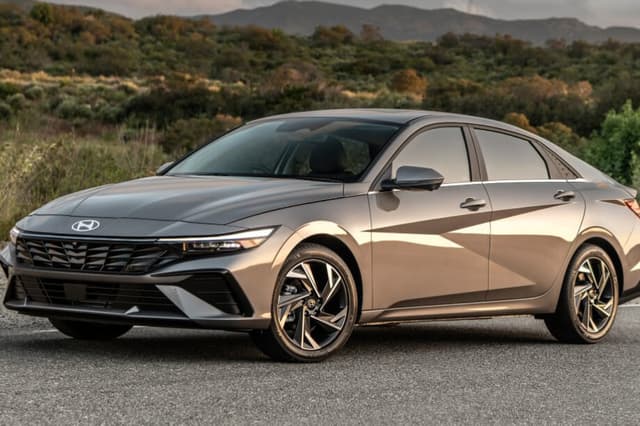
2024 Hyundai Elantra
 Mileage: | 51600 km | 42600 km |
 Years: | 2022 | 2021 |
 Fuel: | Benzin + Plin | Benzin + Plin |
 Color: | White | Gold |
 Location: | Tampa, FL | Tampa, FL |
 Interior: | Jet Black | Jet Brown |
 Engine: | 1.5L Inline | 2.5L Inline |
 Transmission: | Automatic | Automatic |
 VIN: | 1G1ZD5ST0PF | 1G1ZD5ST0PF |
 Stock Number: | 165921 | 165921 |
Quick View
18 sold in last 32 hours
Fog Light Lamp White/Yellow Dual Colors
$90.00
$128.99-25%Only for Audi European Version Q3,Not fit US. Version Q3. SZSS-CAR Car tail light Replacement for Audi Q3 2016 2017 2018.
• Color
Left(driver) side• Specific
Third Brake Lights• Source
HalogenQuantity:
Bessie Cooper is the Chief Financial Officer at Aurexo, Inc. responsible for financial strategy, accounting operations, tax compliance and investor relations. Oliver has over 10 years of experience in senior corporate finance & strategy roles across several high-growth consumer brands, having joined the company Flexcar.
Prior to Flexcar, Oliver was VP of Strategy at Leaf Group Ltd., a publicly traded Internet, media, and ecommerce company where he was responsible for driving profitable growth strategies for its two-sided marketplace business, Society6. Prior to Leaf Group, Oliver was Director of Finance at Ogin, Inc., a private equity backed clean technology company. He began his career in corporate advisory and M&A at Capstone Advisory Group.
Infomation


